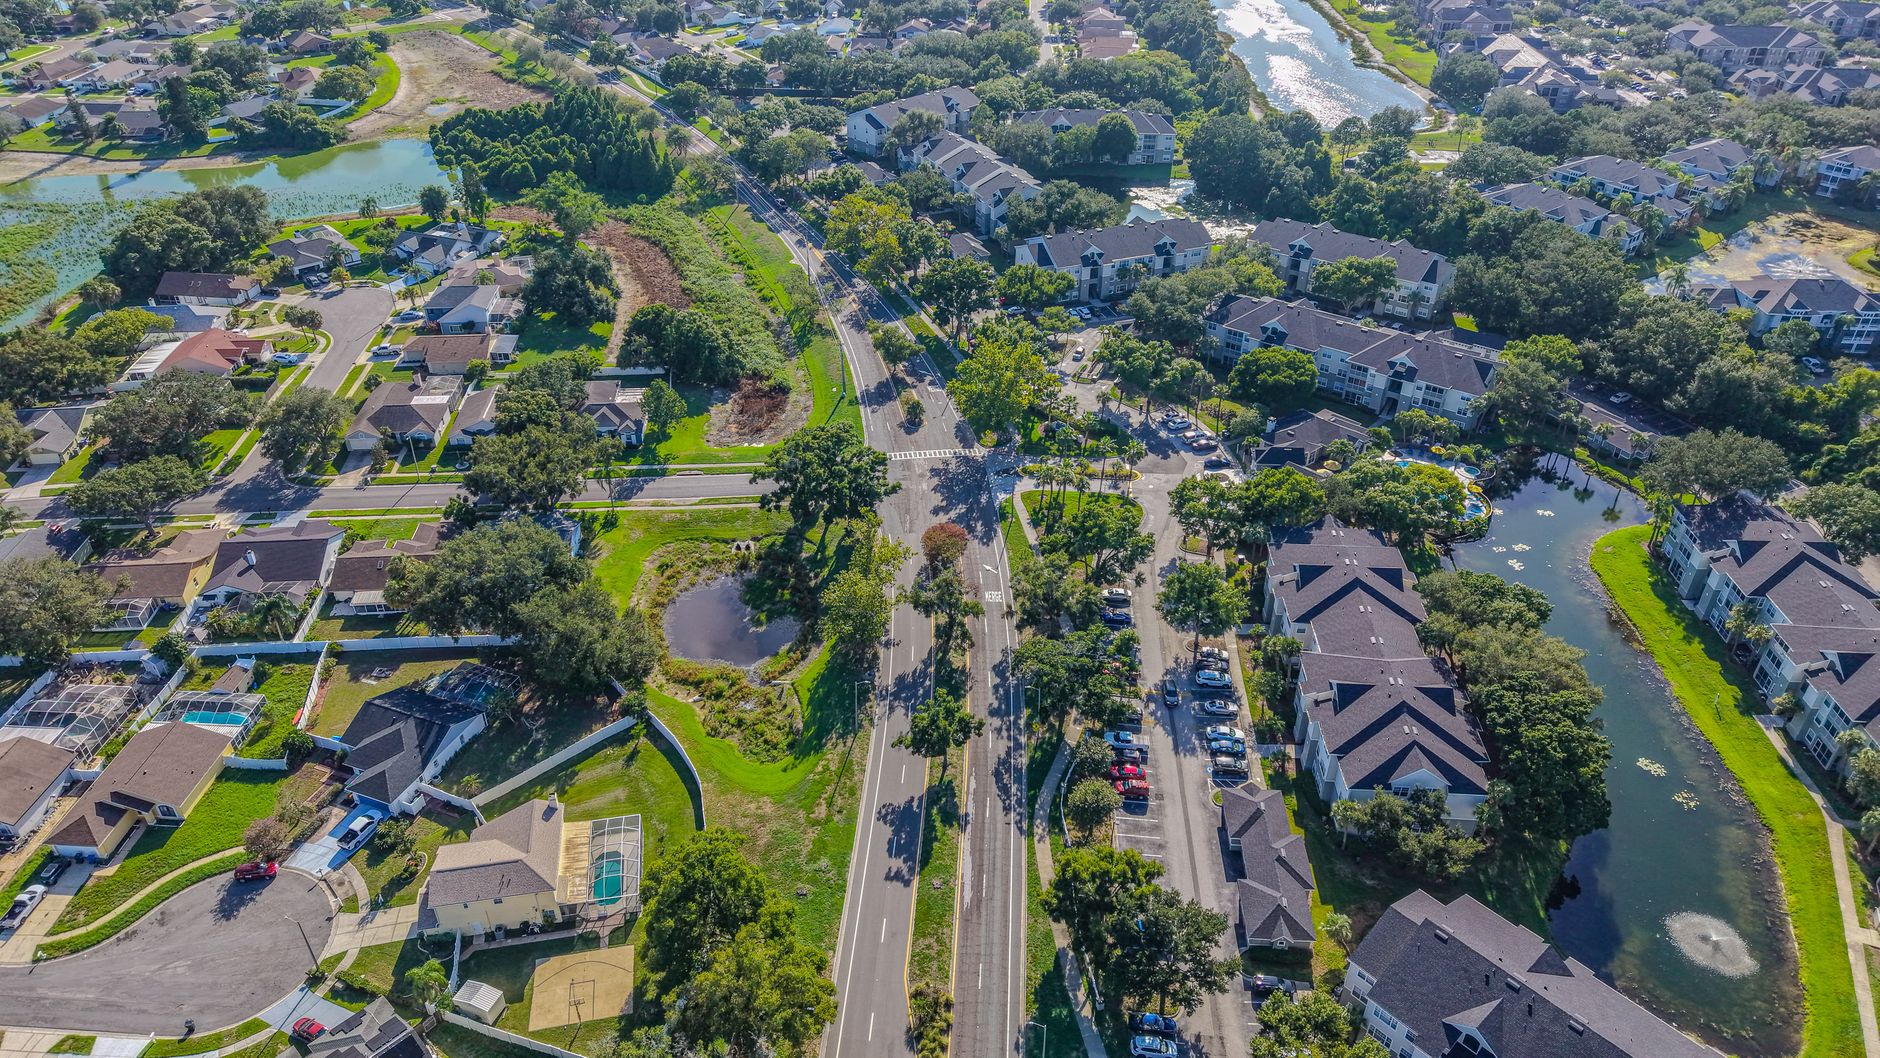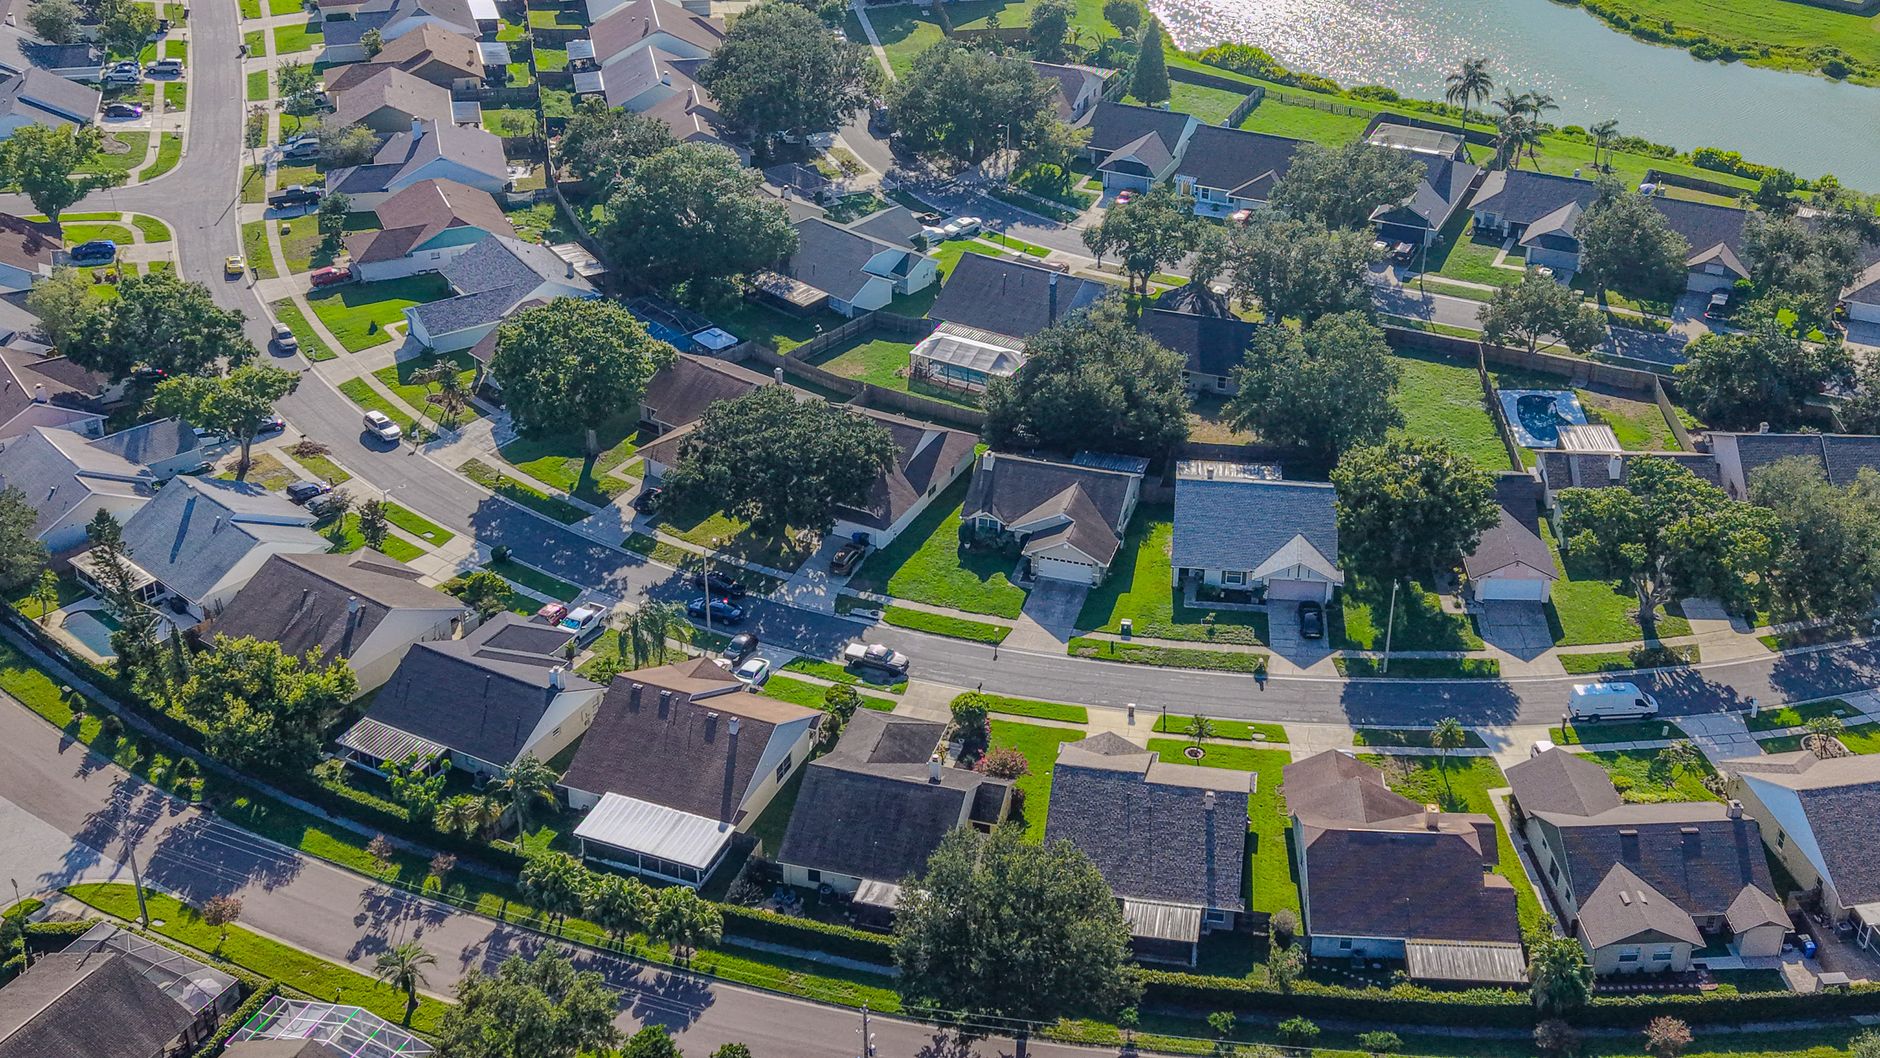
You've probably seen the headlines calling Tampa a buyer's market. Inventory is up. Days on market are stretching. Price cuts are everywhere. That story is mostly true.
Here's what almost nobody is saying alongside it: Tampa just led the entire country in luxury home price appreciation. Not Florida. Not the Southeast. The country.
Those two facts exist simultaneously - and the gap between them is more important than either number alone.
What the data actually shows at the top of the market
According to a Redfin report covered by the Business Observer in early September 2026, the median sale price for a luxury home in Tampa for the three months ending in July was $1.64 million - and that figure represents price growth that outpaced Miami, West Palm Beach, and every other metro in the country over that same period.
Meanwhile, non-luxury Tampa prices rose just 0.3% year over year. Not 3%. Not 13%. Zero-point-three. Essentially flat.
The metro average is the worst tool for making a neighborhood decision. When you blend a 15%-plus luxury surge with a nearly static non-luxury market, you get a headline number that accurately describes almost nothing happening on the ground.
Tampa's housing market is not one market. It's two markets wearing the same zip code - and most buyers and sellers are using the wrong map.
If you're pricing a home in South Tampa, Hyde Park, or Davis Islands above $1.2M, stop benchmarking against the metro median. You're operating in a separate market with different demand drivers, different buyer profiles, and different negotiation dynamics. Pull luxury comps only - and pull them from the last 60 days, not 6 months.
Why the luxury market is climbing while the rest is flat
This isn't random. There are three forces converging at the top of the Tampa market right now, and they don't exist with the same intensity in the sub-$600K segment.
- Rate insensitivity: Buyers at $1.5M and above are disproportionately cash buyers or buyers with significant equity from higher-cost markets. A 6.5% mortgage rate is an inconvenience for them. For a first-time buyer at $380,000, it's a wall. That asymmetry is widening the performance gap between market tiers.
- Inbound migration from expensive metros: Tampa has been absorbing buyers leaving coastal California, New York, and Chicago for years. Those buyers didn't leave their wealth behind. A $1.6M home in Hyde Park still looks like a discount to someone who sold a $3M condo in Manhattan. That arbitrage trade isn't slowing down.
- Supply constraints at the top: You can build a new production home in Wesley Chapel or Riverview. You cannot build a new waterfront estate on Davis Islands or replicate a walkable block in Seminole Heights. Scarcity at the luxury tier is structural. Inventory expansion - which is real and meaningful across the broader market - hasn't reached the segment where supply is geographically constrained.
If you're a luxury buyer currently sitting on the sidelines waiting for a price correction, understand what you're actually waiting for. In geographically constrained neighborhoods with strong migration demand, the correction may not come - and the cost of waiting is compounding. Run the math on what a 12-month delay costs you if prices continue appreciating at even half the current rate.
Why the non-luxury flatline is not the same story in every neighborhood
The 0.3% non-luxury figure is a metro-wide average, which means it's smoothing over some real divergence at the neighborhood level.
Hillsborough County median prices are hovering around $390,000 to $408,000, showing modest year-over-year gains of roughly 2% to 4% depending on the data source. Pinellas County - covering Clearwater and St. Petersburg - is sitting near $375,000 as inventory ticks up. Pasco County, with Wesley Chapel and New Port Richey driving volume, is closer to $340,000 - making it one of the only genuinely affordable entry points left in the metro.
Some zip codes in Pinellas and Pasco have seen values dip 3% to 6% from their 2024 peaks. That's not a catastrophe, but it's also not nothing - especially if you bought near the top with minimal equity cushion and are now looking at insurance premiums that have risen faster than your home's value.
In a market this fragmented, every neighborhood is making its own argument for value - and buyers who understand that have a structural advantage over those reading metro headlines.
If you're shopping in Pinellas or northern Pasco right now, request a hyperlocal price trend chart by zip code before you make an offer. A neighborhood down 5% from peak and a neighborhood up 3% from peak can sit 10 minutes apart. Knowing which one you're in changes your negotiation posture entirely.
What insurance is doing to this split - and why it matters more at the bottom
Here's the dimension that almost never appears in the luxury-versus-non-luxury conversation: insurance costs hit non-luxury buyers proportionally harder.
A buyer purchasing a $450,000 home in a Pinellas flood zone is carrying an insurance burden - sometimes $6,000 to $10,000 annually between homeowners and flood coverage - that represents a far larger percentage of their housing payment than a buyer at $1.6M. Risk Rating 2.0 repriced flood insurance based on individual property characteristics, not zone averages. That change punished the mid-range coastal market in ways that the luxury market could absorb and the non-luxury market often couldn't.
I've talked with several agents working the Clearwater and Dunedin corridors who describe deals falling apart not on price, but on insurance quotes that arrive during due diligence. The home passes inspection. The buyer can't stomach the carrying cost. That dynamic doesn't appear in any price index, but it's shaping which homes sell and which ones sit.
Insurance is doing more to segment the Tampa Bay market than mortgage rates are - and almost nobody is framing it that way.
Before you fall in love with a Pinellas or Hillsborough coastal property, run an insurance estimate during the showing - not after you're under contract. Citizens Insurance eligibility, flood zone designation, and wind mitigation rating all affect the annual cost significantly. I've seen buyers save $4,000 a year simply by selecting a home one block outside a high-risk zone. That's a real number worth knowing before you write an offer.
What this means for sellers across both tiers
If you're selling a luxury property in Tampa right now, the data is working in your favor in a way it isn't for most of the metro. National demand, limited supply, and a buyer pool that's rate-insensitive create conditions where aggressive pricing can still be defended - provided the product genuinely competes at that level. Condition and presentation matter more at $1.5M than anywhere else, because luxury buyers have options and they're not settling.
If you're selling in the $350,000 to $700,000 range, the picture is more honest. Active listings across the Tampa-St. Petersburg-Clearwater metro are up roughly 14% to 18% year over year. Homes are sitting longer. The buyers who are in the market have real choices and real leverage. Pricing correctly from day one isn't just good advice - it's the only strategy that works in this environment. Overpriced listings in this tier are effectively funding comparable homes that are priced right.
My read on this
The luxury surge is real, and it tells you something important about Tampa's long-term trajectory - this city is genuinely attracting high-net-worth buyers, and that doesn't reverse quickly. But I wouldn't use it to draw comfort if you're operating in the non-luxury tier. Those are different markets with different supply, different buyer motivation, and different sensitivity to insurance and rates.
The number I'd watch most closely right now is days on market by neighborhood - not the metro average. When a specific neighborhood's median days on market starts compressing, that's the earliest signal that demand is returning to that price point before it shows up in the sold prices. By the time prices move, the leverage has already shifted.
If I were buying under $500,000 today, I'd be patient but not passive. The inventory advantage buyers have right now is real, but it won't last indefinitely if rates soften. If I were selling in that same range, I'd stop watching what luxury homes are doing and start watching what the house two streets over just sold for. That's the only comparable that actually matters.
Questions I'm hearing
Is the Tampa luxury real estate market still strong in 2026?
Yes - Tampa led the nation in luxury home price appreciation for the three months ending July 2026, with a median luxury sale price of $1.64 million. Demand from out-of-state buyers and limited supply in waterfront and walkable neighborhoods are driving that strength.
Are Tampa home prices dropping in 2026?
It depends on the price tier and neighborhood. Non-luxury prices are up just 0.3% metro-wide, and some zip codes in Pinellas and Pasco are down 3% to 6% from 2024 peaks. Hillsborough is showing modest gains of 2% to 4%. There's no single answer that fits every part of the market.
Why is there such a difference between Tampa's luxury and non-luxury housing markets?
Luxury buyers are largely insensitive to mortgage rates, draw from a national pool of high-equity migration buyers, and compete for supply that's geographically constrained. Non-luxury buyers face rate pressure, rising insurance costs, and significantly more inventory to choose from - all of which shift pricing power toward buyers in that segment.