You've probably seen the headlines saying now is a great time to buy in Tampa Bay. And for once, the data actually backs that up.
But here's what almost nobody is mentioning alongside it: the number your lender gave you is not your monthly payment. Not in Tampa Bay. Not in 2026. And buyers who don't understand that distinction are getting surprised at the closing table - or worse, renegotiating deals they should have priced correctly from day one.
The opportunity window is real. The budget math most buyers are using is not.
Why November is genuinely different in Tampa Bay
A Redfin report published this week identified early November as the single best time of year to buy a home in Tampa. The reasoning is specific, not seasonal fluff. Todd Edwards, a Redfin Premier agent in Tampa, put it plainly: "Local buyers have a good shot at getting a deal in November, mainly because it's just before the snowbirds arrive." Sellers want to close before the new year, and out-of-town competition hasn't picked up yet.
That timing overlaps with a broader market shift that's been building all year. Homes in Tampa are receiving an average of one offer and selling in around 63 days, with a median sale price of $418K - down 7.5% year-over-year. Days on market have stretched from 47 to 63 compared to the same period last year. Sellers who have been sitting since summer are running out of patience.
The metro average is the worst tool for making a neighborhood decision - but even at the metro level, the direction is clear: leverage has shifted to buyers, and it peaks right now.
If a listing has been active since June or July in Westchase, Carrollwood, or Brandon, run the days-on-market math before you write the offer. A seller sitting on 130+ days in this market is not holding firm on price - they're waiting for someone to show up. That someone should be a prepared buyer with a realistic full-payment number, not a lowball offer that insults them into digging in.
The number your lender gave you is missing $500 to $1,300 a month
Here's where the real problem starts. A buyer gets pre-approved for a $400,000 home. The lender quotes principal and interest. Maybe taxes get folded in. Insurance is estimated at $150-$200 a month because that's what the national average looks like. They shop. They fall in love with a 1978 block home near the coast in St. Pete. Then the insurance quote comes back.
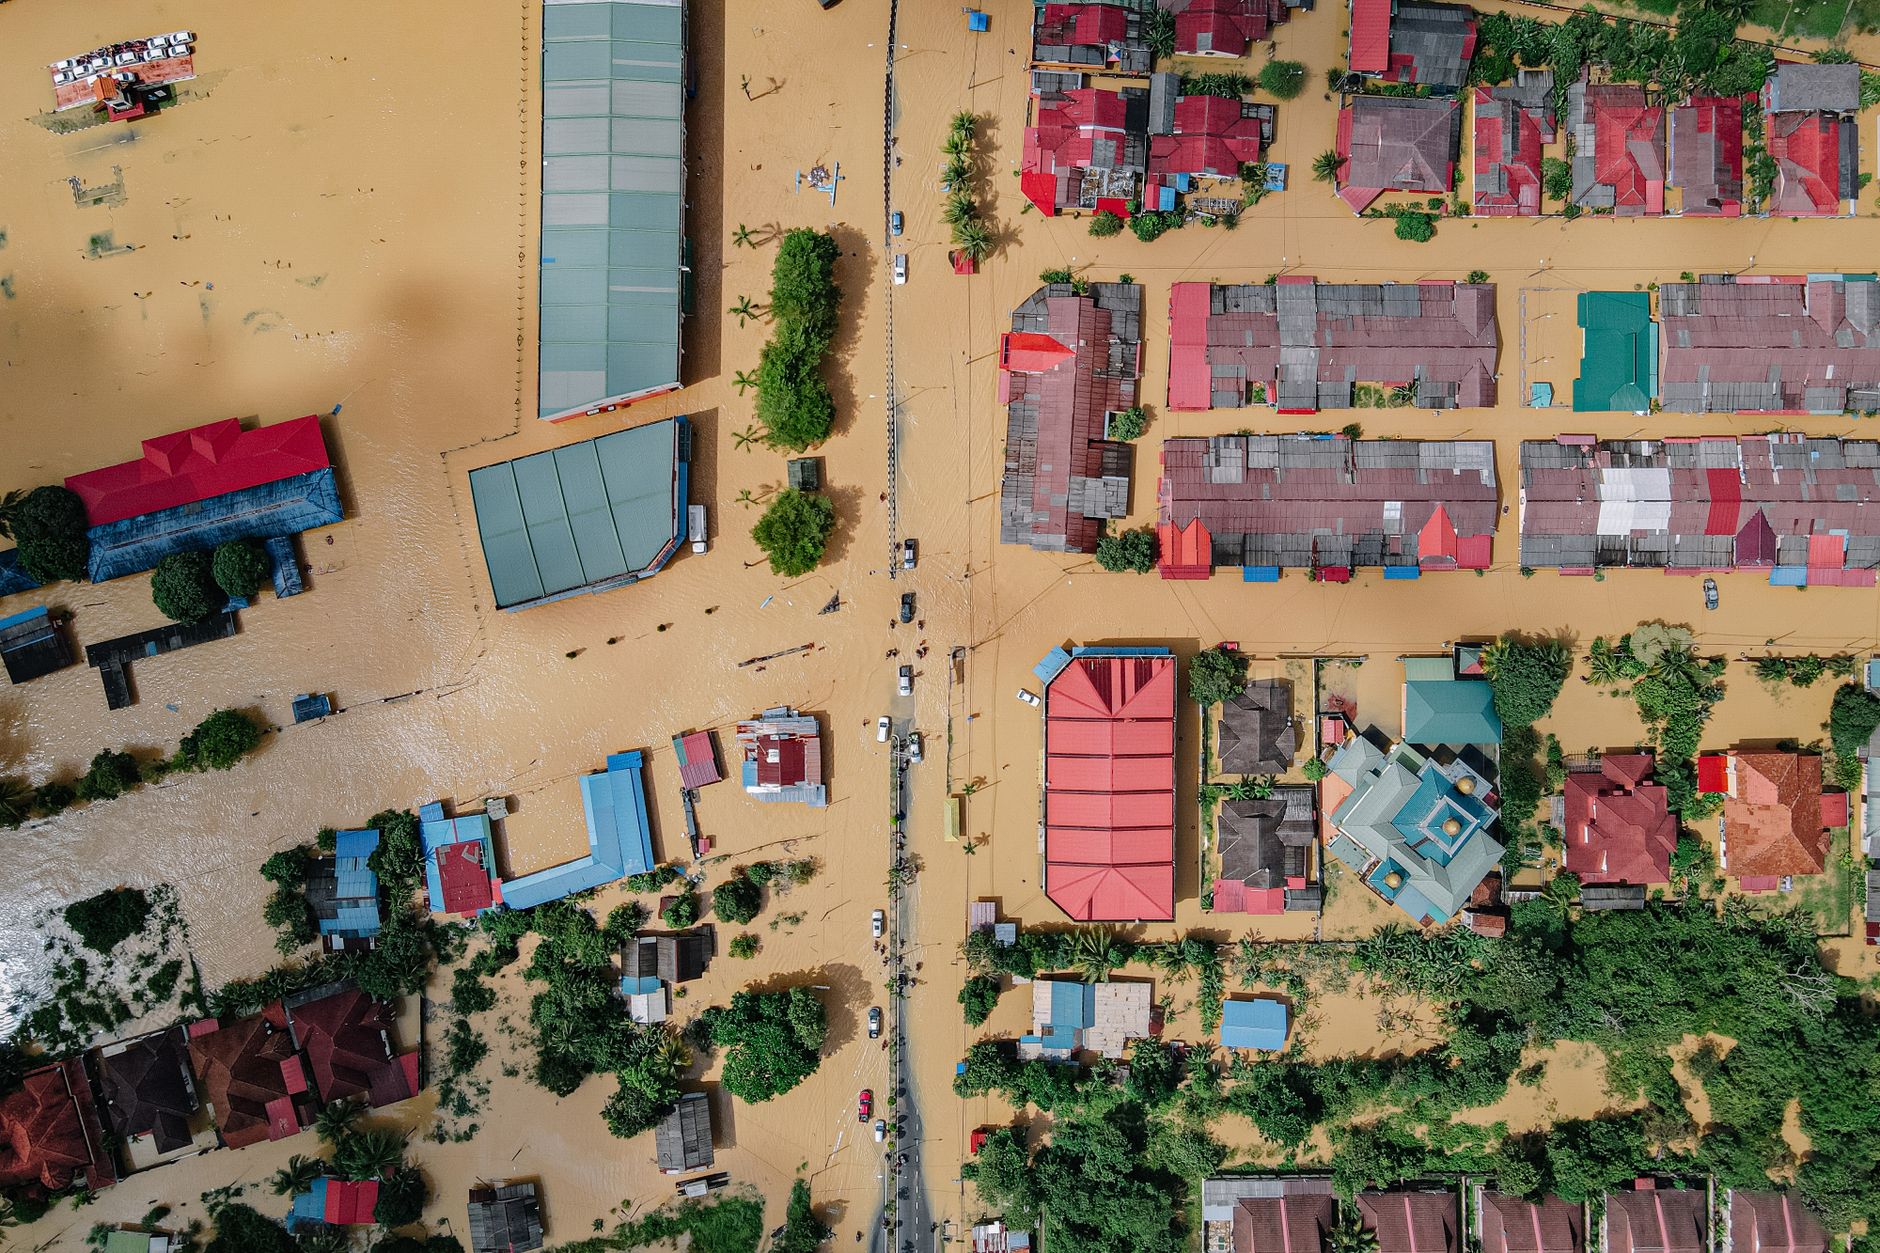
It's a real scenario: a buyer offered $430K on a 1978 home in a flood zone, the insurance quote came back at $9,200 per year - $767 a month. They had budgeted $400 a month. They renegotiated to $395K or would have walked. That is not an edge case. That is Tuesday in this market.
County-level averages for a policy with $300,000 in dwelling coverage and a 2% hurricane deductible tell the real story: Hillsborough County averages roughly $4,971 per year. Pinellas County averages roughly $5,564 per year. Manatee County averages roughly $5,302 per year. And those are the baseline numbers - before flood insurance is added for any property in Zone AE.
For a $700,000 home near the coast in Pinellas or South Tampa in Zone AE, homeowners coverage runs roughly $5,500 to $9,000, plus flood coverage anywhere from $2,800 to $10,000 or more - totaling $700 to $1,300-plus per month, with a wind mitigation report treated as required homework.
Insurance is deciding more deals than price - and most buyers don't run the real number until it's too late.
Before you make an offer on anything in Tampa Bay, pull the flood zone designation and get an actual insurance quote - not an estimate from your lender's software. Call an independent Florida insurance broker with the property address. This takes 48 hours and can save you from a deal that looks good on paper and destroys your budget at closing. I've watched buyers skip this step and then spend weeks trying to renegotiate instead of close.
Why the ZIP code matters more than the county average
The county averages above are already eye-opening. But the variance within those counties is where buyers make or lose thousands of dollars per year without realizing it.
A homeowner in ZIP code 33703 - Shore Acres and Snell Isle in St. Petersburg - can easily pay $7,000 to $12,000-plus per year when a standard HO-3 policy is stacked with mandatory NFIP flood coverage in Zone AE. That's roughly $600 to $1,000 per month in insurance alone - on top of a mortgage, taxes, and any HOA dues.
Meanwhile, a buyer in Kenwood, Allendale, or Disston Heights in interior Pinellas - Zone X, no mandatory flood coverage - might pay $2,500 to $3,800 per year total. Same county. Completely different financial reality.
This is not abstract. When a buyer calculates their total monthly cost and insurance adds $500 to $1,500 per month, it directly reduces what they can offer for the home. That math is working against coastal and flood-zone sellers whether they acknowledge it or not.
- Shore Acres / Snell Isle (33703, Zone AE): Combined insurance exposure of $7,000-$12,000-plus per year. Buyers must factor full flood + hazard before qualifying.
- South Tampa near Bayshore (Zone AE): Older construction, coastal adjacency, and elevated flood exposure stack premiums fast. Wind mitigation inspection is non-negotiable before closing.
- Seminole Heights / Ybor City (Hillsborough, Zone X): Generally lower flood risk than coastal Pinellas. Insurance closer to the county baseline, sometimes less.
- Wesley Chapel / Land O' Lakes (Pasco, Zone X): Inland homes in Zone X run roughly $2,700 to $4,500 per year for homeowners coverage, with optional flood around $1,000 to $1,400. This is where total cost-of-ownership most closely matches what a lender pre-approval assumes.
- Dunedin / Clearwater Beach coastal properties: Several carriers non-renewed coastal policies in flood-prone zip codes and raised rates 15-30% through 2025 and into 2026. Confirm what's actually insurable before falling in love with the view.
If you're comparing a $420,000 home in Shore Acres to a $420,000 home in Seminole Heights, you're not comparing the same purchase. Run both through a full monthly cost analysis: mortgage, taxes, HOA, and actual insurance quotes. The Shore Acres home could cost $800-$1,100 more per month to own. That's the real comparison - and it changes the math on which home is actually the better buy.
What the condo market is telling us that single-family buyers should hear
Tampa Bay condos and townhomes are sitting at more than 13 months of supply - a clear buyer's market driven by the HOA insurance and assessment crisis. That segment is the leading indicator for what happens when insurance costs are not managed proactively.
Tampa Bay condo values have declined 8-12% from their peaks, driven by SB 4-D reserve requirements mandating structural inspections and fully funded reserves for older buildings, special assessments of $30,000 to $150,000-plus per unit in some complexes, and insurance costs that have doubled or tripled for many condo associations.
The condo market is not a different story - it's the single-family market's preview of what happens when carrying costs outpace perceived value. Single-family coastal sellers are not immune to that same logic. They're just about 12 to 18 months behind condos in feeling it.
The one thing that lowers your insurance number before you close
There is a move buyers can make right now that most skip because their agent doesn't bring it up: request the wind mitigation report and 4-point inspection from the seller as part of due diligence, before the offer is written if possible, or as a contingency condition if not.
Credits from a favorable wind mitigation report can reduce the wind portion of a premium by 20 to 45%, and the inspection itself typically costs only $150 to $250. On a coastal Pinellas home paying $6,000 per year in windstorm coverage, that's a potential savings of $1,200 to $2,700 annually - real money, recurring, every year of ownership.
A new roof in 2026 costs $15,000 to $30,000 for a typical Pinellas single-family, but the premium savings plus the higher sale price often justify it before listing. If a seller hasn't replaced their roof and the home has been sitting, that's a negotiating point - either ask for a credit at closing to cover it, or use the projected insurance cost differential to justify a lower offer price.
Ask for the seller's current insurance declarations page as part of your due diligence request. It tells you what carrier insures the home, what they're actually paying, and whether the home has had recent claims that could affect your ability to get coverage at a reasonable rate. It's public-facing data once you're under contract, and most sellers will provide it. The ones who won't are telling you something.
My read on this
November is real. I've watched enough Tampa Bay cycles to know that the window between summer inventory sitting and snowbird demand arriving is one of the few moments where a prepared buyer has genuine leverage without competing for it. Sellers who listed in June and are still active are not holding out for a better offer - they're holding out for any reasonable offer. That's a different negotiation.
But the buyers I'd be concerned about right now are the ones who are pre-approved, excited, and completely unprepared for the insurance conversation. In Tampa Bay in 2026, the mortgage is often the smallest surprise in the monthly payment. The insurance is where deals fall apart, where buyers lose six weeks renegotiating, and where homes that look like great values quietly aren't.
If I were buying right now, I'd move fast on the market timing - but I'd run the full cost-of-ownership number on every home before I got emotionally attached to any of them. Zone X inland properties in Seminole Heights, Carrollwood, or Wesley Chapel give you the best shot at a monthly payment that matches your pre-approval. Coastal Zone AE properties in South Tampa or Pinellas can still be great buys - but only if the insurance math works before the offer goes in, not after.
The opportunity is here. Don't bring the wrong budget to it.
Questions I'm hearing
Is November actually a good time to buy a home in Tampa Bay?
Yes - and there's data behind it, not just seasonal intuition. Early November is the peak season for buying as homebuying slows ahead of the holidays, leaving sellers with fewer potential buyers - and in Tampa, that dynamic is amplified by the timing just before snowbirds arrive. Sellers who have been on market since summer are motivated to close before year-end, and competition from out-of-town buyers hasn't materialized yet.
How much is home insurance in Tampa Bay in 2026?
Homeowners insurance for a typical single-family home in Tampa Bay runs $2,500 to $5,500 per year for the hazard and windstorm policy alone in 2026, per Florida Insurance Department data. But that number can double or triple when flood coverage is added for properties in FEMA Zone AE - and many coastal neighborhoods in Pinellas and South Tampa carry that designation. Always get a real quote tied to the specific address before making an offer.
Are Tampa Bay home prices dropping in 2026?
The median sale price in Tampa was $418K as of the most recent data, down 7.5% year-over-year. But that number masks major neighborhood variation. Condos are declining faster than single-family, coastal and flood-zone properties face more price pressure than inland homes, and correctly priced move-in-ready homes in strong submarkets are still moving quickly. The metro number tells you the direction - not your specific deal.
Curious what the real monthly cost looks like on a specific property you're eyeing? Send me the address. I'll pull the flood zone, run the insurance scenario, and show you what it actually costs to own it - not just what it costs to finance it. No pitch, just the math.